
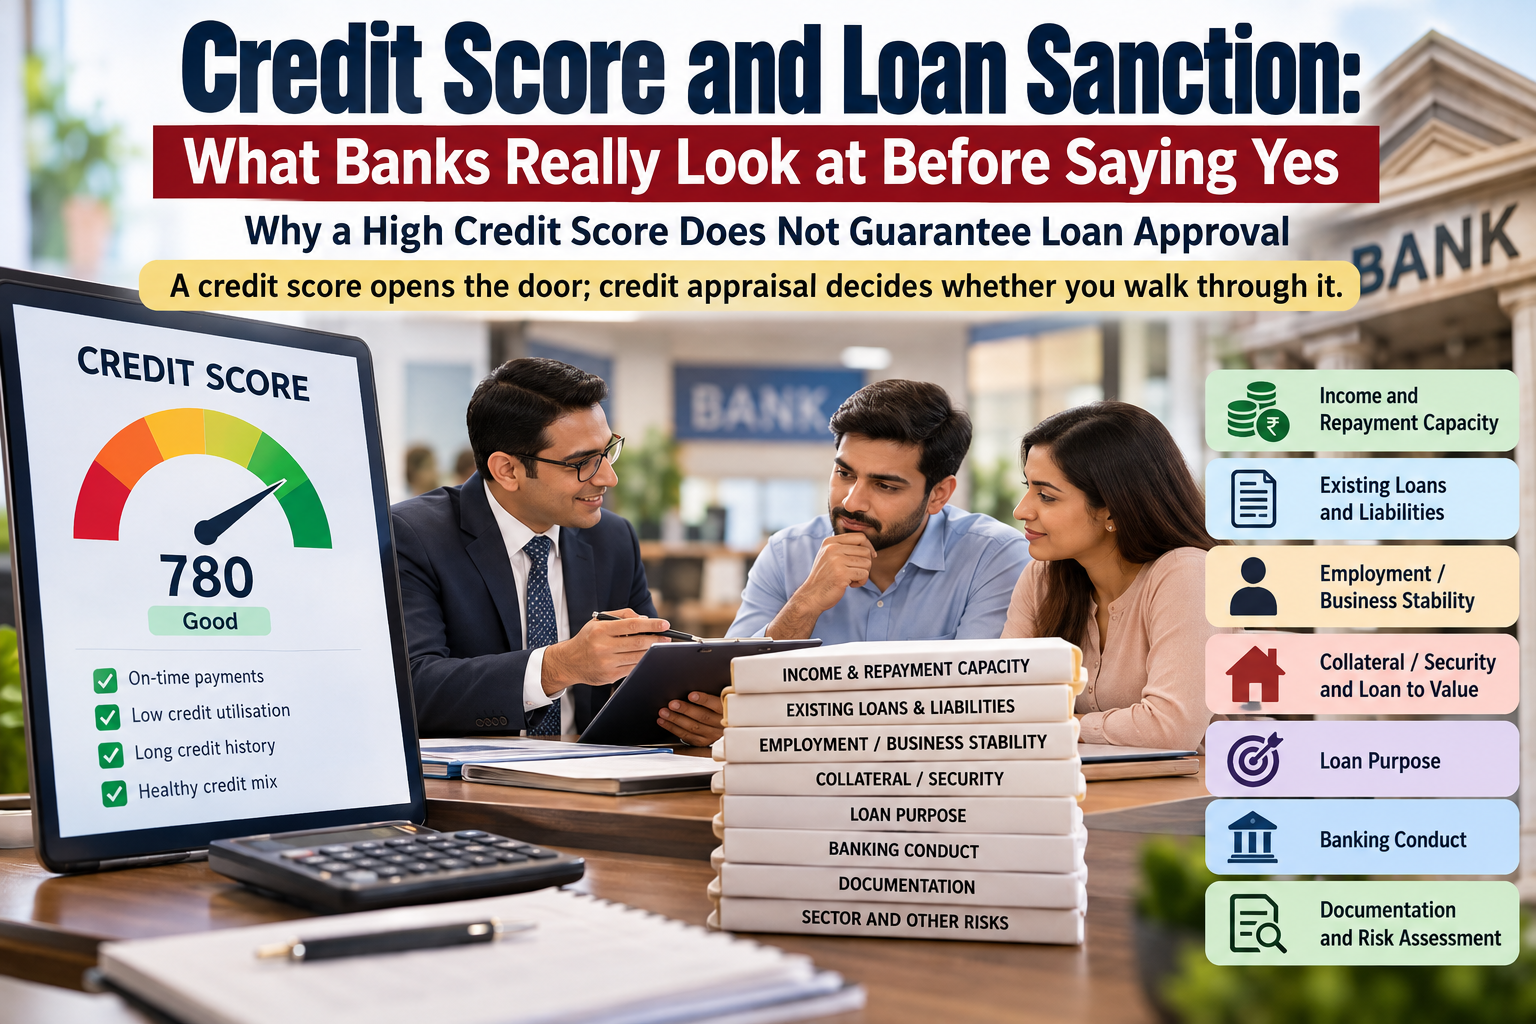
Credit Score and Loan Sanction: What Banks Really Look at Before Saying Yes
Why a High Credit Score Does Not Guarantee Loan Approval
A credit score opens the door; credit appraisal decides whether you walk through it.
Introduction: Is Your Credit Score Enough to Get a Loan?
When a person applies for a home loan, vehicle loan, personal loan or business finance, one of the first questions asked is: “What is my credit score?” A good score creates confidence, while a lower score often creates concern. Over time, the credit score has become one of the most visible indicators of a borrower’s financial reputation.
There is, however, an important distinction that every borrower, professional and banker should understand.
A credit score reflects how you managed credit in the past. Credit appraisal examines whether you can repay the proposed loan in the future.
A high score is therefore important, but it is not a guarantee of loan sanction. Banks and other lenders undertake a broader credit appraisal before committing their funds. They examine income, repayment capacity, existing liabilities, employment or business stability, collateral, loan purpose, banking conduct, documentation and the risks attached to the borrower’s business or sector.
This article explains the process in simple language for borrowers, members of the general public, professionals, business owners and bankers.
1. What Is a Credit Score?
A credit score is a three-digit number that indicates how a borrower has handled credit in the past. In India it generally falls in the range of 300 to 900 and is generated by credit information companies such as TransUnion CIBIL, Experian, Equifax and CRIF High Mark. Lenders report repayment and credit-related information to these companies, which use it to prepare credit reports and scores.
The most important word here is “past”. A score describes historical borrowing behaviour. By itself it does not establish what the borrower’s income, expenses, liabilities or repayment capacity will be during the future tenure of the proposed loan. That is why a credit score should be viewed as one component of the lending decision, not the entire decision.
2. How Is a Credit Score Generally Influenced?
The exact methodology of each credit information company is proprietary, but the broad factors are well known.
Repayment history. Whether EMIs, credit card dues and other obligations were paid on time is a major factor. Repeated delays, defaults, write-offs or settlements can adversely affect the profile.
Credit utilisation. This is the share of the available credit limit that is being used. If a credit card has a limit of ₹1,00,000 and the outstanding balance is ₹80,000, utilisation is high. Lower utilisation is generally viewed more favourably than consistently using a large part of the limit.
Length of credit history. A longer record of responsibly maintained credit gives more information about borrowing behaviour.
Credit mix. The nature of the facilities, such as secured and unsecured borrowing, may also form part of the profile.
Recent enquiries. Numerous applications for loans or cards within a short period lead to multiple enquiries and may raise concerns about the borrower’s immediate need for credit.
There is no single credit-score threshold that guarantees loan approval. Different lenders may apply different internal credit policies and eligibility criteria. A higher score generally reflects a stronger credit history, but the final lending decision depends on the borrower’s overall financial and risk profile.
3. What a Credit Score Tells a Bank, and What It Does Not
A credit score primarily answers one question: how has this borrower handled credit in the past? It does not fully answer another equally important question: can this borrower comfortably repay the new loan being requested?
That second question needs a much broader assessment, and this is the fundamental difference between credit scoring and credit appraisal. A borrower may have an excellent credit history but insufficient income for the proposed loan. Conversely, a borrower with a less impressive score may have other financial strengths that deserve evaluation. A good score is therefore better understood as a starting point for appraisal, rather than a promise of sanction.
4. Income and Repayment Capacity: Can the Borrower Actually Pay?
For a lender, the most fundamental issue is repayment. The bank wants to know whether the borrower will have sufficient and reasonably predictable cash flow to meet the proposed EMI throughout the loan tenure. The appraisal may therefore examine gross monthly income, net take-home income, business cash flows, household expenses, existing EMIs, other fixed obligations, the proposed EMI and the stability of income.
A person earning Rs.1,00,000 per month may appear financially comfortable. But if a large part of that income is already committed to existing loans and other obligations, the capacity to take another loan may be limited.
5. Understanding FOIR
The Fixed Obligation to Income Ratio, or FOIR, broadly compares the borrower’s monthly fixed obligations with net monthly income. In simplified form:
FOIR = Total Monthly Fixed Obligations ÷ Net Monthly Income × 100
Suppose the net monthly income is Rs.1,00,000, existing EMIs are Rs.25,000 and the proposed EMI is Rs.20,000. Total obligations are Rs.45,000, so the FOIR is 45 per cent.
Some lenders may use FOIR parameters in a broad range around 40–50 per cent for particular products or borrower categories, but the applicable level varies by lender, product, income profile, risk assessment and internal credit policy.
FOIR matters because the bank is not merely asking whether the borrower can pay today’s EMI. It is also asking whether enough income will remain after servicing debt to meet normal living or business expenses and to withstand reasonable financial stress. A high credit score cannot compensate indefinitely for inadequate repayment capacity.
6. Employment and Income Stability
The amount of income is important, but the stability and verifiability of that income are equally important.
Salaried borrowers. Banks may examine total work experience, the current employer, length of service with the present employer, salary credits, continuity of employment and the nature of the job.
Self-employed borrowers and business owners. The appraisal may focus on business vintage, income tax returns, GST returns, bank statements, financial statements, profitability, cash flows and continuity of the business. A business reporting a large turnover but weak or inconsistent cash generation may need closer examination.
The principle is simple: a lender is interested not merely in reported income, but in sustainable and verifiable repayment capacity.
7. Existing Debt Burden
Before granting another loan, a bank looks at the borrower’s existing commitments, such as home loans, vehicle loans, education loans, personal loans, business loans, credit card dues and other disclosed obligations.
A borrower may have an excellent repayment record and still have limited capacity for additional borrowing. The issue is not past repayment discipline but the future debt burden once the proposed loan is added. A borrower who is already financially stretched may find it difficult to service one more EMI, particularly if income falls or unexpected expenses arise.
8. Loan-to-Value Ratio: How Much Is the Bank Financing Against the Asset?
In secured lending, the bank also looks at the loan amount divided by the value of the security. This is the Loan-to-Value ratio, or LTV. For example, if a property is valued atRs.1 crore and the proposed loan is Rs.75 lakh, the LTV is 75 per cent. The higher the LTV, the greater the lender’s exposure relative to the value of the security.
Applicable regulatory requirements and the lender’s internal policy may limit the amount that can be financed against a particular asset. If the requested loan exceeds the permissible level, the lender may reduce the loan amount or require a higher contribution from the borrower. Even a strong credit profile cannot eliminate LTV requirements.
9. Collateral Quality and Legal Title
For a secured loan, the security offered must be legally enforceable and capable of supporting recovery if repayment fails. Banks may therefore examine ownership records, title documents, the chain of title, encumbrances, approved building plans, regulatory approvals, valuation, the physical condition of the property and other legal and technical aspects, often through independent verification.
A property with a defective title, an unresolved dispute, inadequate approvals or another material defect can create a serious lending problem, even where the borrower’s personal credit profile is strong.
An important lesson for borrowers: do not wait for the bank’s legal scrutiny to discover a problem with the property. Before committing substantial money to buy a property that is proposed to be mortgaged, have the title and relevant documents examined appropriately.
10. Purpose and Type of Loan Matter
The risk attached to different types of lending is not identical. Home loans are generally supported by identifiable immovable property, and vehicle loans by the financed vehicle. Loans against deposits have a different security structure. Personal loans are generally unsecured, while start-up and unsecured business financing may involve greater uncertainty about future cash flows.
The nature and purpose of the loan therefore influence the lender’s assessment and the extent of due diligence required. Borrowers should be clear about the purpose, amount and repayment source of the proposed borrowing.
11. Age and Remaining Earning Years
Age can affect eligibility and tenure. Banks generally consider whether the loan can be repaid within the borrower’s remaining earning period. Where a borrower is approaching retirement, a lender may restrict the maximum tenure, depending on its policy and the availability of post-retirement income.
A shorter tenure generally means a higher EMI, a heavier monthly repayment burden and, potentially, a lower eligible loan amount. In appropriate cases, an earning co-applicant may help address some tenure and repayment-capacity concerns, subject to the lender’s policy.
12. Banking Relationship and Account Conduct
The way accounts have been run provides useful information about financial discipline. A lender may look at cheque returns, ECS or auto-debit failures, regularity of transactions, account balances, the conduct of existing loan accounts and repayment behaviour with the same lender. Repeated dishonours may raise concerns about liquidity or account management.
At the same time, account conduct is one part of the overall appraisal and should not be treated as an isolated factor.
13. Industry and Business Risk
For business borrowers, the bank does not examine only the individual or the company. It may also examine the business environment, including industry outlook, market conditions, competition, the regulatory environment, cyclicality, the business model, the sustainability of cash flows and other sector-specific risks.
A business may be managed honestly and professionally and yet operate in an industry facing volatility or regulatory uncertainty. The lender may then adopt a cautious approach based on the risks of the sector as a whole.
14. Why May a Loan Be Declined Despite a Good Credit Score?
This is one of the most misunderstood aspects of borrowing. A borrower with a good score may still face difficulty because of:
- Insufficient income for the amount of loan requested.
- High existing EMIs that already consume a substantial part of income.
- Multiple recent credit applications, which may need additional explanation or assessment.
- Employment instability, such as frequent job changes or gaps in employment.
- Property-related problems, such as a defective title, inadequate approvals or technical concerns.
- Business or industry risk, including weak business performance or sector-specific concerns.
- Internal lending policy, since every lender has its own credit policy, risk appetite and eligibility parameters, which may include specific parameters for borrower categories, industries or geographical areas.
These factors do not necessarily reflect on the borrower’s honesty or character. They represent the lender’s assessment of future credit risk.
15. How Does the Credit Appraisal Process Work?
The procedure differs among banks and financial institutions, but a typical application passes through several stages.
Preliminary screening. Basic eligibility is checked, such as age, income, employment, loan purpose and basic documentation.
Credit bureau review. The lender obtains and examines the credit report and repayment history.
Document verification. KYC documents, income proof, bank statements, income tax returns, GST records, financial statements and property documents are verified.
Field investigation. Where required, the residence, workplace, business premises or other relevant details are physically verified.
Internal credit assessment. The lender combines all available information and evaluates the overall risk.
Sanctioning authority. The proposal goes to the appropriate authority according to the lender’s delegation of powers, the loan amount and the risk parameters.
Sanction letter. If approved, the borrower receives a communication setting out the loan amount, tenure, interest rate, conditions and other applicable terms.
16. What Should a Borrower Do Before Applying for a Loan?
A little preparation can prevent avoidable problems.
- Check your credit report well in advance and seek correction of any genuine errors.
- Pay EMIs and credit card dues on time.
- Keep credit utilisation under control.
- Review your existing debt and understand your total monthly obligations.
- Where financially appropriate, clear smaller loans or card balances to reduce monthly obligations.
- Avoid applying to several lenders at the same time.
- Keep ITRs, salary records, bank statements, GST returns and financial statements properly maintained.
- For property-backed loans, check the title and documents early, before committing to the transaction.
- Maintain good banking conduct and avoid cheque returns and ECS failures.
- Consider the tenure carefully, since a longer tenure lowers the monthly EMI but generally increases the total interest payable over the life of the loan.
17. Should a Borrower Consider an Earning Co-Applicant?
In appropriate cases, an earning co-applicant can strengthen a loan application. A co-applicant may bring additional income, greater repayment capacity, a potentially lower combined FOIR, additional financial stability and, in some cases, a longer permissible tenure.
However, becoming a co-borrower is not a mere formality. A co-applicant may also carry repayment obligations under the loan documents. A person should therefore agree to become a co-applicant only after understanding the financial and legal implications. The objective should not simply be a larger loan. It should be to keep the borrowing sustainable for the persons responsible for repayment.
18. A Word for Bankers and Credit Professionals
The lesson works in both directions. For the borrower: do not assume that a good credit score guarantees sanction. For the banker: do not assume that the score alone represents the entire credit risk.
A credit score is an efficient screening and risk-assessment tool, but sound lending requires examination of cash flows, repayment sources, existing obligations, business viability, the quality and enforceability of security, documentation, industry risk, account conduct and overall financial circumstances.
A high score should not become a substitute for proper appraisal. Similarly, a less favourable score should not necessarily end the assessment without considering the underlying circumstances and the lender’s applicable policy. Good credit decisions rest on documented reasoning, consistency, proper due diligence and clear communication. This matters for asset quality, and equally for public confidence in the lending process.
The Central Lesson: Past Behaviour and Future Capacity
The whole subject can be understood through one distinction.
Credit score looks backward: How did the borrower handle credit in the past?
Credit appraisal looks forward: Can the borrower repay the proposed loan in the future?
That is why a borrower should not approach a loan application by asking only, “Is my credit score good enough?” The better questions are:
- Is my income sufficient?
- Are my existing obligations manageable?
- Is the proposed EMI affordable?
- Is my employment or business stable?
- Are my financial records consistent?
- Is the collateral legally and technically acceptable?
- Is the loan amount appropriate for my financial position?
- Is the proposed borrowing sustainable over the entire tenure?
Conclusion: A Good Credit Profile Is More Than a Number
A credit score is an important indicator of financial discipline. It deserves attention and should be protected. But a credit score is not the whole credit profile.
Banks and other lenders generally take a broader view that includes credit history, income and repayment capacity, FOIR, employment or business stability, existing debt, LTV, collateral quality, legal title, loan purpose, age and tenure, banking conduct, business viability, industry risk, documentation and the overall risk profile.
The key message is simple: your credit score tells a lender how you managed credit in the past. Credit appraisal helps the lender judge whether you can repay the proposed loan in the future.
For borrowers, understanding this distinction helps them prepare more responsibly and avoid preventable problems. For bankers and credit professionals, it reinforces the importance of looking beyond the score and undertaking a balanced, documented and reasoned appraisal.
Disclaimer
This article is intended for general awareness and educational purposes only and should not be treated as legal, financial, credit or lending advice. Lending criteria and policies may vary among institutions and may change from time to time. The examples are illustrative only. Readers should consider their individual circumstances and seek appropriate professional advice where necessary.
Message to Readers
Dear Readers,
Your credit score is worth protecting, but it is only one part of your financial story. Before applying for a loan, take some time to look at your income, existing EMIs, credit report, documents, banking conduct and overall financial position, just as a banker would. Check your credit report periodically and, if you notice an error, take steps to have it corrected early.
If a loan application is declined, do not treat the decision as a reflection of your financial character. Try to understand the reason, identify the area that needs improvement and consider applying again when your financial position and documentation are better prepared.
Borrowing should not be viewed merely as an opportunity to obtain money. It is a financial commitment that must remain manageable throughout its tenure.
I hope this article helps ordinary borrowers understand what happens behind the scenes when a bank evaluates a loan application, and offers a useful perspective to professionals and bankers as well.
If you found this article useful, please share it with family members, friends, colleagues and business associates who may be planning to borrow.
Ashok Kakkar