
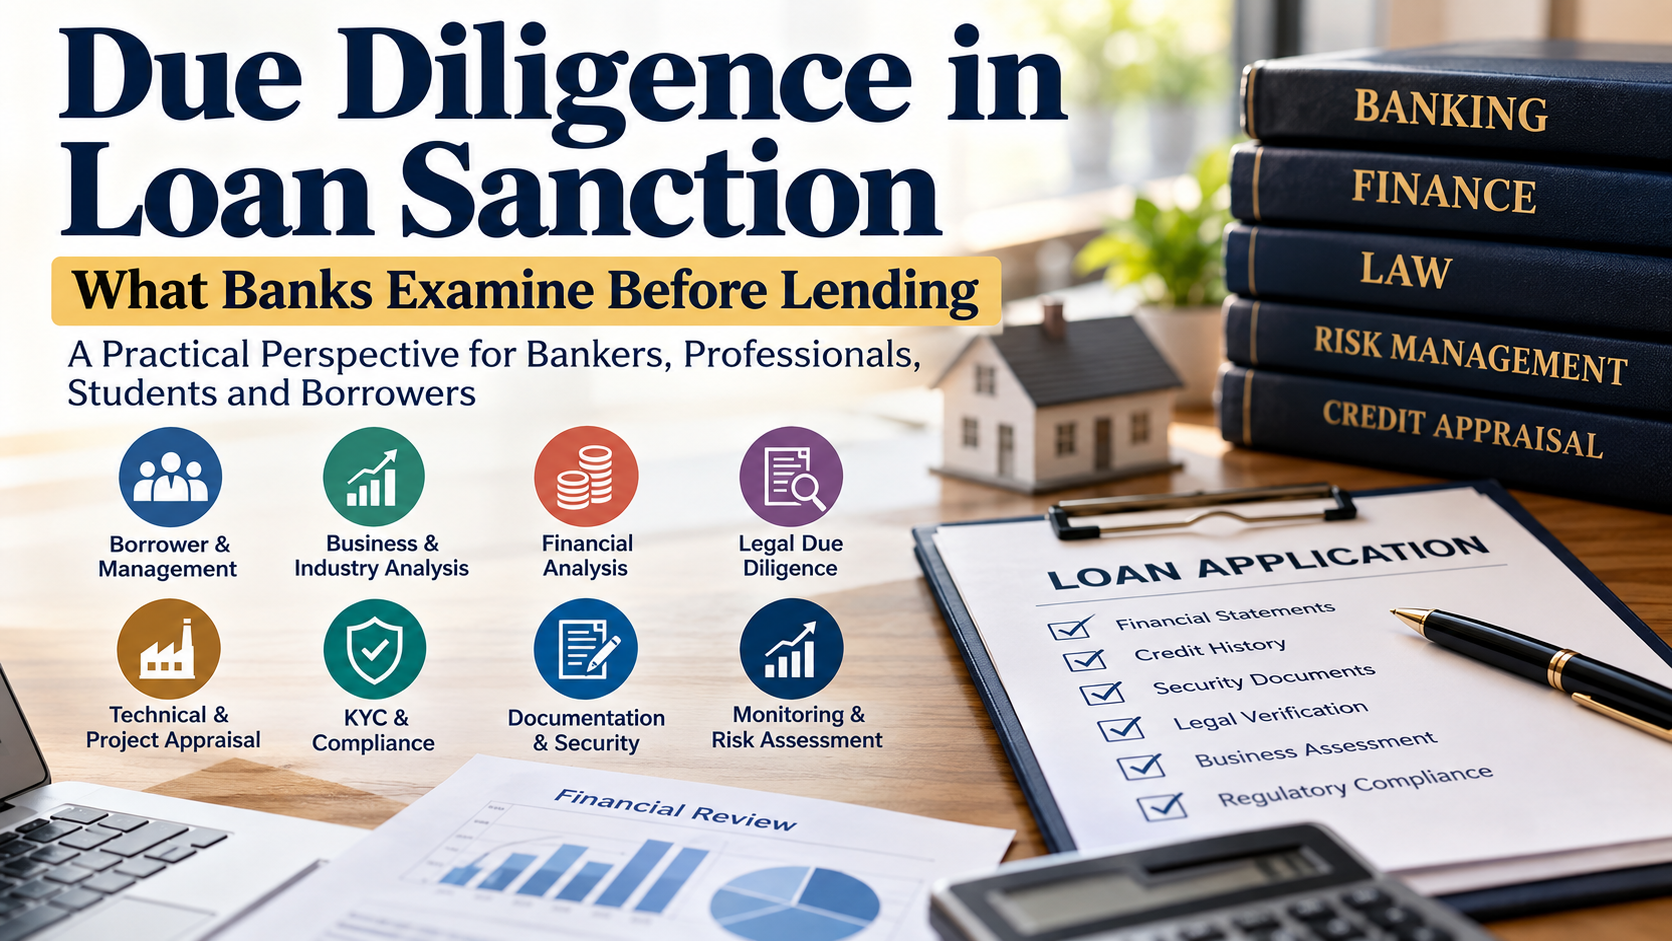
Due Diligence in Loan Sanction: What Banks Really Examine Before Lending
A Practical Perspective for Bankers, Professionals, Students and Borrowers
By Ashok Kakkar
Advocate | IBBI-Registered Insolvency Professional | Former Banker
Introduction
Bank lending sits at the centre of the financial system. Businesses rely on it for working capital, expansion and investment; individuals rely on it for housing, education and personal needs. But every lending decision carries risk — the amount sanctioned has to come back, with interest, on the agreed terms. A business that looks sound today can run into difficulty tomorrow because of a market shift, a cash-flow squeeze, over-borrowing, or simple mismanagement.
This is why due diligence is not a formality — it is the foundation of responsible lending.
It should never be understood as merely collecting documents before disbursing funds. It is the process of genuinely understanding the borrower, the business, its financial position, the purpose of the borrowing, the security offered, and everything that could affect repayment. In practical banking, the real question a banker asks is not “what security is available?” — it is:
“Does this borrower have a genuine, sustainable capacity to repay — and are the bank’s interests adequately protected if things go wrong?”
Answering that question honestly requires looking at the proposal from several angles.
1. Understanding the Borrower
Credit appraisal begins with understanding who is actually asking for the money. For an individual, this means financial position, existing liabilities, credit history and repayment behaviour. For a business, it goes further — because repayment depends entirely on the business continuing to perform.
The promoters’ background, experience and track record matter here. Their history in the line of business, past ventures, financial discipline and general approach to banking obligations all tell a story worth reading. Where the borrower belongs to a larger business group, the relationships and transactions between group entities deserve equal attention, since stress in one can quietly spread to another.
The objective is simple: before lending, the bank should know who is borrowing and who will actually be responsible for running the business and generating the cash to repay it.
2. Understanding the Business and Industry
A financial statement tells only part of the story — a banker also needs to understand the business behind the numbers. The products or services, the market, the competition, the key customers and suppliers, and the availability of raw material all shape a business’s real ability to generate revenue.
A business can look strong on paper while operating in a market facing declining demand, or while depending too heavily on one or two customers whose orders could disappear tomorrow. Historical performance therefore needs to be read alongside the current environment and future prospects — not in isolation.
3. Financial Due Diligence — Looking Beyond Profit
Financial statements remain central to any lending decision, but turnover and profit alone don’t tell the full story. A proper review tracks the movement of sales, profitability, debt, receivables, inventory and cash flow over time, supported by ratios covering liquidity, leverage, interest coverage and debt-servicing capacity.
One principle matters more than any single ratio: profit is not cash flow. A business can report a profit and still struggle to repay its bank borrowing — because its funds are tied up in receivables or inventory, or because it is carrying excessive debt elsewhere. A loan is ultimately serviced from real cash generation, which is why the central question in financial due diligence is: will this business generate enough cash, consistently, to meet its obligations?
Independent verification adds a crucial cross-check to whatever the borrower submits. The CIBIL report and other bureau data reveal the credit score, repayment history and recent loan inquiries — a score above 750 is generally reassuring, but the trend matters as much as the number. Cross-checking with Experian, Equifax or CRIF High Mark adds further confidence. A CERSAI search confirms whether the offered security is already charged elsewhere; an ROC charges search does the same for corporate borrowers. The RBI’s Wilful Defaulter List, the ECGC Caution List, SEBI’s debarred entities list, and the bank’s own internal records complete this layer of verification.
4. Examining Working Capital Requirements
For most businesses, working capital sits at the heart of the banking relationship. The bank needs to understand how much capital the operating cycle genuinely requires — purchasing raw material, processing, holding inventory, selling, and finally collecting receivables — and how any mismatch in that cycle creates pressure on liquidity.
A borrower may need finance not because the business is unprofitable, but simply because its funds stay locked up in stock and receivables for a period of time. Working capital assessment, in other words, cannot be separated from the real operating cycle of the specific business in front of the banker.
5. Legal Due Diligence of the Security
Security is a major part of most lending transactions — but its existence alone doesn’t make a loan safe. The bank has to confirm that the person offering the security genuinely holds the rights over it, and that the bank’s interest can be legally created and enforced. For immovable property, this means examining title documents, ownership, existing charges and encumbrances — supported, where needed, by an independent legal opinion.
The distinction worth remembering: a valuable asset is not necessarily an enforceable security. A property may look attractive on paper, but title defects, prior claims or weak documentation can quietly reduce its real value to the bank. Value and enforceability both have to be established — not assumed.
6. Technical and Project Due Diligence
This becomes especially important for project and term loans. It covers feasibility — cost, location, implementation timeline, machinery, infrastructure and approvals — along with independent technical assessment and valuation where relevant. A project can look financially attractive on paper and still run into trouble because of cost escalation, delays or a shift in market conditions. The goal is to establish that a project is technically feasible, not just financially appealing.
7. Market and Operational Assessment
No business operates in isolation. Shifts in demand, competition, input costs, technology or policy can all affect a borrower’s performance, so a banker needs to test whether the assumptions behind projected turnover and profitability are actually supported by the business environment. Customer concentration and supplier dependence deserve particular attention here — both can turn a seemingly stable business into a fragile one almost overnight.
8. KYC and AML Compliance
Before deeper financial or legal checks begin, the borrower’s identity and standing must be established — Aadhaar, PAN, passport and address for individuals; incorporation documents and board or partner resolutions for entities — along with screening against RBI, SEBI and UN sanctions lists, and reporting of suspicious transactions under the Prevention of Money Laundering Act, 2002. These are not -paperwork for its own sake; they are part of how the bank manages customer risk.
9. Identifying Warning Signals
One of the most valuable outcomes of due diligence is catching an issue early. A sudden, unexplained rise in turnover, unusual transactions, unrealistic projections, excessive leverage, significant related-party dealings, frequent ownership changes, or reluctance to share information — all of these warrant a closer look.
A red flag doesn’t automatically mean rejection. It means the matter needs further investigation before a decision is made. The real skill in credit appraisal lies in telling the difference between a normal business circumstance and a genuine warning sign.
10. Site Visit and Personal Interaction
Documents tell a great deal — but not everything. A visit to the business premises, and direct conversation with the promoter or management, often reveals things financial statements never will: the real scale of operations, the condition of machinery and inventory, and how genuinely involved management is in the day-to-day running of the business. These observations should support financial and documentary evidence, not substitute for it.
11. Documentation — The Legal Shield
Once due diligence is complete and a loan is sanctioned, documentation becomes the bank’s primary legal safeguard. The sanction letter records the terms; the Demand Promissory Note is an unconditional promise to repay, enforceable under the Negotiable Instruments Act, 1881; mortgage or hypothecation deeds secure the assets offered; guarantee agreements bind third parties where applicable; and registration with the ROC and CERSAI protects the bank’s priority. A well-appraised loan can still turn into a difficult recovery if the paperwork behind it is weak. Good appraisal and good documentation have to go together.
12. Due Diligence Does Not End at Sanction
Credit appraisal shouldn’t stop the day a loan is disbursed. After that, the bank needs to stay alert to the borrower’s ongoing position — changes in turnover, stock, receivables, account conduct, repayment behaviour, ownership or management can all be early signs of stress, and the end-use of funds and adequacy of security deserve continued monitoring. Credit management works best as a continuous cycle — appraisal → sanction → documentation → disbursement → monitoring → early identification of stress — rather than a one-time exercise.
13. The Role of Professional Judgement
Technology, credit scoring and data-driven models have made appraisal faster and more consistent — but they haven’t made professional judgement optional. A banker still has to step back and ask: does the overall story make sense? Do the financials match the real business? Are the projections realistic? Is the security genuinely enforceable? Are the promoters capable of steering the business through a rough patch? These questions, more than any single ratio, are what separate a routine appraisal from meaningful due diligence.
Conclusion
Due diligence in loan sanctioning is not a checklist of documents to be gathered and filed away. It is a genuine effort to understand the borrower, the business, the cash flows, the legal position, the security and the risks that could affect repayment.
For a banker, it leads to a more informed lending decision. For a borrower, it explains why a bank asks the questions it does. For a professional or insolvency practitioner, understanding the original appraisal often explains how — and why — an account later moved into stress. For a student, it shows how the textbook concepts of finance actually play out in a real credit decision.
Collateral should never overshadow the most fundamental question in lending: how will this borrowing actually be repaid? A loan isn’t successful merely because it gets sanctioned — its real quality shows in whether it comes back, on time, with interest.
A Message to Readers
Whether you’re a banker, a borrower, a professional or a student, it helps to look at a loan from both sides of the table. For the banker, lending means balancing opportunity against risk. For the borrower, taking a loan means accepting the obligations that come with it, not just the funds. Good lending begins with genuine understanding — and good borrowing begins with understanding what you’re taking on.
Ashok Kakkar
Disclaimer: This article is for general informational purposes only and reflects the author’s professional experience. It is not legal, financial or credit advice, and due diligence requirements vary by institution and case. Readers should seek appropriate professional advice before acting on any point discussed here.
#Loan Sanction, #Due Diligence, #Credit Appraisal, #Bank Lending, #Credit Risk, #Working Capital, #Loan Documentation, #CERSAI, #Banking Awareness, #NPA Management,